
Expert Tips for Navigating the Business Loan Process

Understanding Your Business Needs
Before diving into the business loan process, it's vital to assess your company's financial needs. Determine the specific reasons for seeking a loan, whether it's for expansion, equipment purchase, or working capital. Understanding your objectives will guide you in selecting the right type of loan and lender.
Consider the amount of funding required and how it aligns with your business plan. Having a clear financial goal helps in convincing lenders of your preparedness and seriousness.
Researching Loan Options
Once you've identified your needs, it's time to research different loan options. There are various types of loans available, such as term loans, lines of credit, and SBA loans. Each type has its own advantages and requirements.
Make a list of potential lenders, including banks, credit unions, and online lenders. Compare their terms, interest rates, and eligibility criteria. This will help you find the most suitable option for your business.
Preparing Your Documents
Documentation is a critical part of the loan application process. Prepare key documents such as financial statements, tax returns, and a detailed business plan. These documents provide lenders with insights into your business's financial health and operational structure.
Ensure that all documents are accurate and up-to-date. Having organized paperwork can streamline the application process and create a positive impression on lenders.
Improving Your Credit Profile
Your credit profile plays a significant role in loan approval. Lenders assess both personal and business credit scores to evaluate risk. Before applying, review your credit reports for errors and take steps to improve your scores if necessary.
Paying off outstanding debts and maintaining a low credit utilization ratio can enhance your credit profile. A strong credit history increases your chances of securing favorable loan terms.
Crafting a Strong Loan Proposal
A well-crafted loan proposal can set you apart from other applicants. Your proposal should clearly outline the purpose of the loan, how it will benefit your business, and your repayment plan.
Include detailed financial projections to demonstrate your ability to repay the loan. Highlight your business's unique strengths and market position to build confidence with lenders.
Communicating with Lenders
Effective communication with lenders is crucial throughout the loan process. Be transparent about your business's financial situation and answer any questions promptly.
Establishing a good relationship with your lender can facilitate smoother negotiations and possibly lead to better loan terms. Remember, lenders are more inclined to work with businesses they trust.
Understanding Loan Terms
Before accepting a loan offer, thoroughly understand the terms and conditions. Pay attention to interest rates, repayment schedules, and any fees associated with the loan. Knowing the total cost of the loan will help you make an informed decision.
If anything is unclear, don't hesitate to ask your lender for clarification. It's essential to be fully aware of your obligations to avoid future complications.
Planning for Repayment
Once the loan is secured, focus on planning your repayment strategy. Create a realistic budget that incorporates loan payments without straining your business's cash flow.
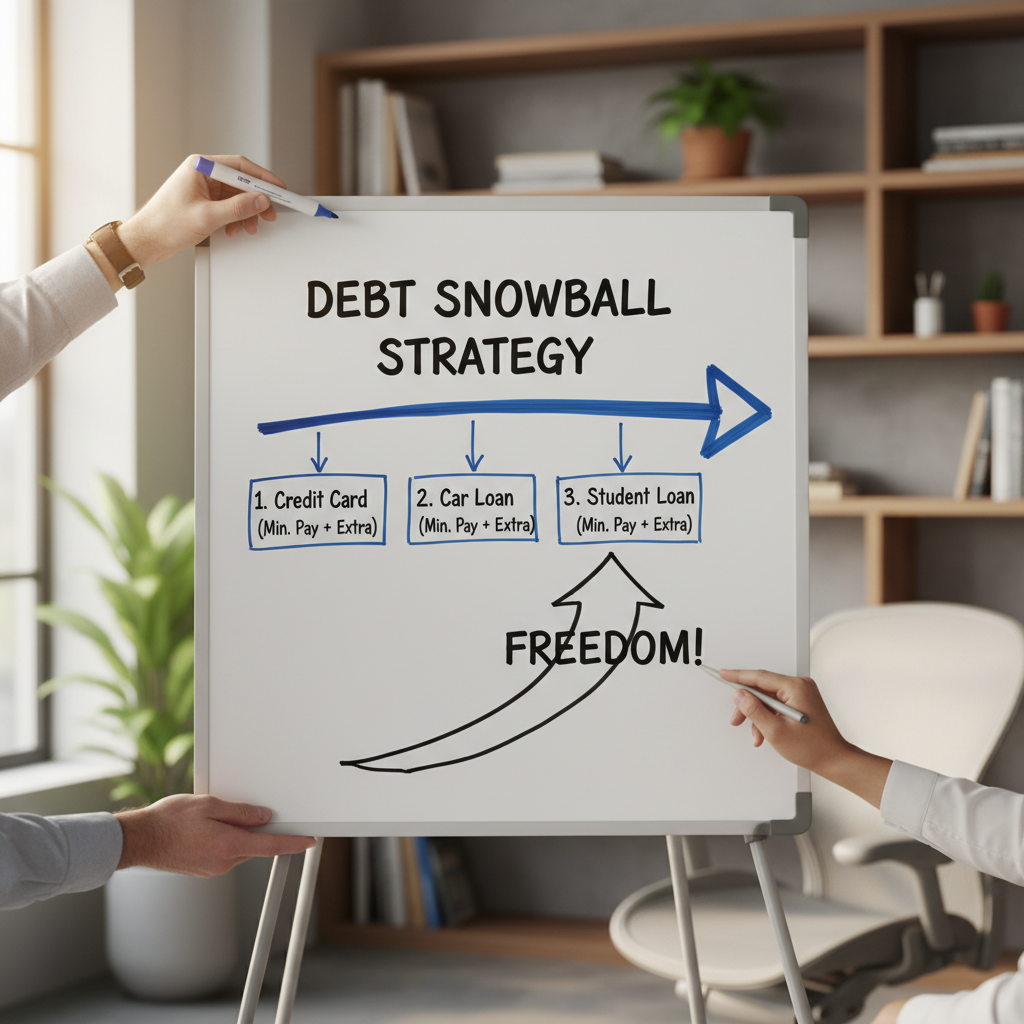
Timely repayments not only fulfill your obligations but also build your business's creditworthiness, making it easier to access future financing if needed.